As an investment consultant and portfolio manager for different clients, I manage a number of different investment strategies. Once you understand my investment philosophy, you’ll understand why I manage these strategies the way I do. I share the investment commentary on these strategies here.
U.S. CORE STRATEGIES
The U.S. Core strategies provide long-term exposure to core U.S. equity and bond markets. The strategies may have some exposure to non-core markets, including foreign assets and lower-quality fixed income. The strategies are structured to participate in the upside of bullish U.S. equity and credit markets. The strategies’ risk exposure is not tactically managed and can result in poor performance in weak U.S. market environments. The U.S. Core strategies utilize mutual funds and ETFs to construct the strategies.
Performance Review
The U.S. Core strategies were mixed in Q3 as dispersion in U.S. equity markets and weakness in bonds drove performance. The more aggressive, equity-heavy strategies were generally flat to positive, while the more conservative, bond-heavy strategies declined in the quarter as higher interest rates pushed bond prices lower. Within equities, the strongest performance was led by positions in large cap value, passive S&P 500 Index, and large cap dividend growth strategies. Negative equity performance was driven by exposure to mid and small cap equities.
The U.S. Core and U.S. Core Muni strategies’ bond allocations were negative in Q3 as interest rates shifted higher, which pushed bond prices lower. All taxable and municipal bond managers posted negative performance in the quarter. Our positions in tactical bond managers were negative, but relatively beneficial, as their underweight duration positioning held up better in the weak bond market environment. Our more interest rate-sensitive bond manager positions were the weakest performers in Q3.
Positioning
Risk Assets
The U.S. Core strategies offer exposure to U.S. equities by combining passive market cap-weighted, smart beta factor, and actively managed approaches. The portfolios are structured to provide diversification across market cap and investment styles, with a preference for higher-quality, growing companies to drive long-term capital appreciation.
Conservative Assets
The U.S. Core strategies provide diversified exposure to U.S. bonds across sectors, credit quality, and duration. We focus our allocations on active bond managers that have the flexibility to deploy capital in the bond markets to take advantage of opportunities and manage risks over the long term.
INCOME STRATEGIES
The Income strategies primarily invest in higher income-generating assets. This can include dividend-paying stocks, option-income strategies, investment-grade bonds, high-yield bonds, emerging markets debt and real estate securities. The strategies’ risk exposure is not tactically managed, which can result in poor performance in weak U.S. market environments. The Income strategies utilize mutual funds and ETFs to construct the strategies.
Performance Review
The Income strategies declined in Q3 as income-generating assets felt pressure from rising interest rates. When bond yields increase, other non-bond income-generating assets often feel the pressure as well and that is what appears to have happened in the quarter. Our strongest performers in the quarter included U.S. and international large cap dividend-oriented strategies, equity option income strategies and our allocation to a multi-asset income manager. The weakest performers in Q3 included closed-end funds, where leverage exacerbated the selloff and discounts to net asset values widened, global real estate income and U.S. mid cap dividend strategies.
Within the Income strategies’ bond allocations, our position in a core intermediate-term bond manager was the weakest performer, as its duration positioning was most impacted when interest rates moved higher during the quarter. Our exposure to tactical bond managers was also weak, as their duration positioning, while underweight relative to core bond benchmarks, still negatively impacted returns. These tactical managers’ positioning helped protect value relative to core intermediate-term bond indices. The performance of our allocation to a short-term, credit-sensitive bond manager was also negative, but the position outperformed the other bond positions due to its lower interest-rate sensitivity.
Our Income – Ultra-Conservative strategy was negative in Q3 as its bond-only portfolio was fully impacted by rising interest rates during the period. All bond manager positions posted negative returns. The strongest relative performers were our allocations to dedicated short-term bond managers, as their limited interest-rate sensitivity was beneficial relative to intermediate-term core bond benchmarks. Our exposure to tactical bond managers and their duration exposure was also a headwind, but their overall positioning helped performance relative to core bond indices. Our exposure to a core intermediate-term bond manager was the weakest performer, as its longer duration relative to our other holdings was a headwind.
Positioning
Risk Assets
The Income strategies seek to balance ongoing income generation with long-term capital growth by allocating across multiple income-generating asset classes and investment strategies. To try to provide income diversification, the Income strategies are allocated across global dividend-paying equities, equity option income strategies, global real estate, closed-end funds and credit-sensitive bonds.
Conservative Assets
In the conservative asset allocation of the Income strategies, generating yield is prioritized through an overweight position in credit-sensitive bonds. We allocate to active short- and intermediate-duration bond managers. We believe their flexible approach has the potential to capture competitive yields while navigating shifting interest rate and credit cycles.
TOTAL RETURN STRATEGIES
The Total Return strategies provide long-term diversified exposure across U.S. and international equities, bonds and income-generating assets. The strategies are structured to participate in the upside of bullish equity and credit markets and provide moderate income generation. The strategies’ risk exposure is not tactically managed and can result in poor performance in weak market environments. The Total Return strategies utilize mutual funds and ETFs to construct the strategies.
Performance Review
The Total Return strategies delivered mixed Q3 results along the risk spectrum. The more aggressive, equity-heavy strategies generated positive returns, while the more conservative, bond-heavy strategies declined in the quarter under the weight of higher interest rates, which pressured the prices of bonds and other interest rate-sensitive asset classes. The strongest performers in the quarter included exposure to the S&P 500 Index, U.S. large cap dividend growth, global value, and international small cap strategies. Our positions in global value and global growth managers were also positive contributors. The weakest performance was driven by exposure to U.S. mid caps, quality large cap international equities, and emerging market equities. Exposure to multi-asset income strategies was mixed, as our allocation to closed-end funds was negative, while our tactical multi-asset income manager position was slightly positive.
In the Total Return and Total Return Muni strategies’ bond allocations, each taxable and municipal bond manager had negative performance in Q3 as interest rates shifted higher during the quarter. The most interest rate-sensitive bond managers experienced the weakest performance in Q3, while the tactical bond managers that were underweight duration and those with less interest rate sensitivity outperformed the others.
Positioning
Risk Assets
The Total Return strategies seek growth and income through globally diversified equity and multi-asset income allocations. We blend U.S. and international equities across market cap and investment styles, while generating additional yield through allocations to tactical multi-asset income and closed-end fund strategies. This structure is designed to pursue growth and income across full market cycles.
Conservative Assets Our Total Return strategies attempt to diversify across bond markets by combining active core and tactical bond managers. We believe this blend provides the flexibility to manage short-term market shifts while staying anchored to long-term objectives
U.S. CORE X STRATEGY
The U.S. Core X strategy provides long-term exposure to core U.S. equity and bond markets. The strategies may have some exposure to non-core markets, including foreign assets and lower-quality fixed income. The strategies are structured to participate in the upside of bullish U.S. equity and credit markets. The strategy is tactical in nature, allowing for the use of leveraged investments to attempt to generate higher returns. The use of leveraged investments can increase the risk of the strategy. Leveraged investments should be considered speculative investments and may not be suitable for all investors.
Performance Review
The U.S. Core X strategy generated slightly positive returns in Q3, while U.S. equities had mixed performance in the quarter. The strongest performance came from positions in a large cap value manager, leveraged and non-leveraged exposure to the S&P 500 Index, and a quality equity dividend growth manager. The weakest performance was driven by losses across leveraged positions, particularly leveraged small and mid caps, and leveraged Dow Jones Industrial Average exposure. Other negative performers in the quarter included non-leveraged exposure to small caps, mid caps, quality growth stocks, and leveraged exposure to the Nasdaq 100 Index.
Positioning
The U.S. Core X strategy attempts to provide diversified exposure to U.S. equities across market cap and investment styles through passive, factor-based, and actively managed third-party managers. The strategy is also tactically allocated to leveraged equity strategies, providing leveraged exposure to U.S. large, mid, and small cap passive equity indices. No tactical adjustments to leverage were made in Q3, and leveraged exposure remains at a neutral target level. If U.S. equities decline to target price levels, leveraged exposure may be increased at that time.
GLOBAL UNCONSTRAINED STRATEGY
The Global Unconstrained strategy provides long-term diversified exposure across U.S. and international equities, bonds and income-generating assets. The strategies are structured to participate in the upside of bullish equity and credit markets and provide moderate income generation. The strategy is tactical in nature, allowing for dedicated positions to attempt to generate higher returns and/or hedged positions to attempt to reduce risk. The strategy may utilize leveraged investments, which can increase the risk of the strategy. Leveraged investments should be considered speculative investments and may not be suitable for all investors.
Performance Review
The Global Unconstrained strategy declined in Q3 as equity and multi-asset income allocations generated mixed results. The strongest performance came from tactical leveraged positions in semiconductors and the Nasdaq 100 initiated in July, while leveraged Chinese equities also delivered strong gains. Among non-leveraged allocations, passive S&P 500 Index exposure, U.S. quality dividend growth, international small caps, and tactical multi-asset income managers all posted positive returns.
The weakest performers in Q3 were both leveraged and non-leveraged exposures to U.S. mid caps and diversified emerging markets. Exposure to closed-end funds also weighed on performance, as their inherent leverage posed a headwind within a challenging environment for income-generating assets, compounded by generally widening discounts to net asset value.
Positioning
Risk Assets
The Global Unconstrained strategy utilizes third-party managers to access a diversified blend of global equities and multi-asset income vehicles. Capital is deployed across market caps and investment styles, with a tilt toward managers focused on higher-quality companies demonstrating sustainable, long-term growth potential.
The strategy maintains its income exposure through a non-leveraged tactical, multi-asset income manager and closed-end funds. Bond yields have risen, credit spreads have slightly widened, and other income-generating assets have experienced some recent weakness. Closed-end fund discounts have also widened beyond historical average levels. For this reason, exposure to closed-end funds was increased in early October, with capital sourced from the allocation to the tactical, multi-asset income manager.
While the portfolio maintains tactical leveraged equity exposure, overall positioning sits near the lower end of its historical range. In late July, amid skepticism surrounding the artificial intelligence trade and a broader selloff in technology stocks, tactical leveraged positions were initiated in the Nasdaq 100 Index and semiconductors by trimming a non-leveraged large/mid cap quality growth manager. Following a sharp Nasdaq 100 rebound through mid-September, the leveraged index Nasdaq 100 position was closed to take profits, with proceeds reallocated back to the quality growth manager. During the quarter, the leveraged semiconductor position was opportunistically rebalanced and remains in the portfolio.
Tactical leveraged positions in Chinese equities, diversified emerging markets and U.S. mid caps remain.
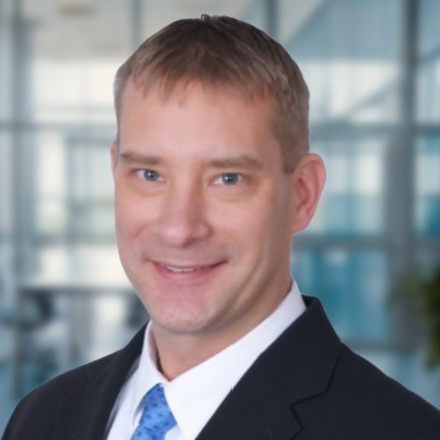
Investment Consultant | Portfolio Manager | Wealth Advisor
Eric is a member of the Larson Financial investment committee and provides private wealth management services through Intrua Financial.
A passionate advocate for financial literacy, Eric also develops multimedia educational courses and market insights designed to demystify complex investment concepts for individual investors.
Prior to his current roles, Eric served as a Senior Portfolio Analyst and Vice President at Robert W. Baird, and previously as a Mutual Fund Specialist at U.S. Bancorp Fund Services.
He is a CFA® charterholder and a CERTIFIED FINANCIAL PLANNER™ professional. Eric earned his Master of Business Administration with a specialization in Finance from Marquette University, graduating with honors, and holds a Bachelor of Business Administration from the University of Wisconsin–Madison.